Autumn Budget 2026

Autumn Budget 2026

The 12 months since the last Budget was delivered have seen significant change.

A more challenging global macroeconomic outlook, yet more inflationary pressures and, perhaps least expected of all, a new Chancellor.

In the weeks leading up to the Budget, many pundits expected a radical change from John Healey, but instead he promised measures that would provide “breathing space” to the UK, as it grapples with a challenging economy and a new cost of living crisis.

Given Andy Burnham’s recent commitments to spending in a number of areas, including housing, defence and social care, it was thought that the speech may include a number of tax raids, but the measures announced were more muted.

With a focus on certainty for businesses and individual taxpayers, Healey’s first Budget contained a plethora of small measures to collect tax and generate investment across many different areas.

As he prepared to take his seat at the end of his speech, he confirmed that the Budget would deliver “breathing space now and hope for the future” after delivering updates and measures in the following areas:

Economic outlook

The Chancellor entered Parliament facing a number of challenges, many of which remain outside of his control.

The ongoing conflicts around the world and persistent inflation meant that the Government is walking a fine line between fiscal responsibility and effective levers for driving economic growth.

This was evident in the Office for Budget Responsibility’s (OBR) latest growth figures:

  • 2026: 1.2 per cent, (up from 1.1 per cent forecast on the Spring Statement)
  • 2027: 1.0 per cent, (down from 1.6 per cent)
  • 2028: 1.6 per cent, (equal to 1.6 per cent)
  • 2029: 1.8 per cent, (up from 1.5 per cent)
  • 2030: 1.7 per cent, (up from 1.5 per cent)

From the beginning of his speech, Healey made it clear that fiscal headroom – the amount available for spending – had fallen from £23.6 billion to £15 billion since March.

As a result, the Chancellor’s war chest was smaller, but still projected to grow.

Seemingly, big announcements on defence spending and further investment in other areas, weren’t included as expected, but will form part of the next spending review.

Taking on the cost of living crisis

This Budget, as the Chancellor announced, was meant to offer “breathing space” and “hope” to businesses and individuals alike.

Announced shortly before the Budget was a number of changes to UK energy costs, with a headline grabbing move to abolish standing charges on gas bills by the end of 2027. This is expected to save the average billpayer £108 a year.

The Chancellor also promised to look into reforming the similar standing charge for electricity bills.

Alongside these measures, it was also confirmed that people living in homes in council tax bands A to D would get a £100 council tax rebate to help with energy costs.

To help manufacturers with rising energy costs, the Government will launch the British Industrial Competitiveness Scheme from 1 April 2027.

This will exempt certain energy-intensive businesses from the indirect costs of the Renewables Obligation, Feed in Tariffs and Capacity Market schemes.

Significant reforms to business rates were also confirmed to help struggling high street businesses.

Pubs, music venues and social clubs will get an additional 20 per cent relief on their business rates bill from 1 April 2027, carrying the full reduction to 35 per cent.

The Government will also increase its Small Business Rate Relief threshold from £12,000 to £18,000 so that a further 70,000 retail, hospitality and leisure businesses pay no business rates at all.

However, many of these businesses will also have to grapple with rising employment costs as a result of the National Living Wage and National Minimum Wage rates rising across the board by 3.9 per cent from 1 April 2027.

The 5p fuel duty cut will also remain in place to help businesses and workers with the sharp increases experienced at the pumps.

Taxing success

With such big spending commitments, tax rises were expected, but what was delivered was nowhere near as significant as earlier speculation had suggested and, in places, remains quite vague.

From April 2027, the lifetime limit for capital gains eligible for Business Asset Disposal Relief (BADR) will be reduced from £1 million to £500,000. This means that any capital gains on an eligible business sale above this new, lower threshold, will be taxed at a rate of 24 per cent for higher-rate taxpayers, instead of 18 per cent enjoyed up to £500,000.

The Chancellor also confirmed plans to review and update the tax rules governing distributions paid by companies to individual shareholders.

The aim is to create a fairer system by limiting arrangements that allow some taxpayers to extract profits in a more tax-efficient manner than others.

Reforms will protect tax treatment for genuine ownership changes, including family business succession, and could offer more generous demerger reliefs.

The Government will consult on the details before implementation in April 2028, but the full details of this change remain sparse.

In a more immediate change, from October 2027, online marketplaces must collect VAT on sales by UK businesses selling more than £90,000 through the platform.

Not a new tax, but a new way of paying tax, will also be introduced for Self Assessment taxpayers. From April 2029, they will pay liabilities in smaller, more frequent instalments throughout the year.

A focus on new business

A large element of the Budget was focused on encouraging entrepreneurship and investment in the UK economy.

From small to large, the Government is taking steps to help with the establishment of new businesses.

For those looking into a new side hustle, the Government is tripling the Trading Allowance from £1,000 to £3,000 from 6 April 2027, to help people looking to make additional income.

A New Founders’ Relief will become available from April 2027 offering a 10 per cent Capital Gains Tax rate on up to £10 million of lifetime gains for founders of qualifying high-growth companies.

An additional £15.4 billion will be pumped into the National Wealth Fund, while the British Business Bank will see its own funds increased by £5 billion to provide investment to up-and-coming UK enterprises.

Further devolution was also mentioned during the speech to help regions set their own spending commitments and the Chancellor was keen to flag that the nation was also open to AI, innovation and data centres, with further information expected in future.

Pensions and investment reforms

There were a number of reforms to tax-efficient investments mentioned in the speech and subsequent Budget documents, but headlines were quickly grabbed by the announcement of a new Pension Tax Allowance.

This will be available from April 2027 to April 2030 to pensioners whose income is at or below the full new State Pension to ensure that they won’t be pulled into paying tax by pension increases. This will work on a taper system that keeps pensioners protected, but ensures higher earners still pay.

The previous cut to Cash ISAs for under 65s was also dropped, so the annual tax-free limit will remain at £20,000.

The Government will, instead, explore a new incentive for people opening a Stocks and Shares ISA for the first time.

A new First Time Buyer ISA will replace the Lifetime ISA for new savers from April 2029.

It pays a 25 per cent bonus on homes worth up to £450,000, capped at £20,000.

From 29 October 2026, the LISA withdrawal charge for buying above the price cap falls to 20 per cent.

Final thoughts

Many expected the Chancellor to deliver significant change, but what emerged was a series of smaller measures that seem to have been designed to deliver stability and calm.

The lack of any significant increases in taxation may surprise many, but with rises spread across a wide area and offset by support and savings in others, the Government may be able to stick to its own fiscal rules, while offering help where it is needed most.
Link: https://assets.publishing.service.gov.uk/media/6ae1ec57bdb574cf1c9b3f12/E03668986_HMT_Budget_2026_ELAY__2_.pdf

The identity verification deadline is almost here

The identity verification deadline is almost here

The Companies House ‘Identity Verification Process’ launched last year on 18 November 2025, making it a legal requirement for new and existing Company Directors and Persons with Significant Control (PSCs) to verify their identity over a 12-month period, as and when their company’s annual Confirmation Statement and PSC ID are due for filing.

This verification process helps deter those wishing to use companies for illegal purposes.

That means Companies House needs to have verified your identity in each of those roles and the 12-month transition period for existing Directors and PSCs ends next month.

We have been writing to clients over the past 12 months when it was time for us to file their company’s annual Confirmation Statement and PSC ID, with full details of how to apply to Companies House for their unique filing code.

A company cannot file its Confirmation Statement until all of its Directors have verified and persistent failure to file can ultimately lead to a company being struck off the register.

All current clients should have received an email from us by now – final notice reminders are going out weekly to those still outstanding, these should be attended to without delay.

What to do now

If you have not already completed the identity verification process, it is extremely important that you forward the unique filing code to us as soon as it has been received from Companies House, as we are unable to file the company’s Confirmation Statement and PSC ID without it and this may incur unnecessary late filing fines and penalties and possible company strike off.

Keeping a toe in the water: Phased retirement

Keeping a toe in the water: Phased retirement

More contractors and consultants are choosing to wind down gradually rather than stop immediately overnight.

We know it can seem appealing and working from one contract to the next lends itself to this approach.

Keeping your limited company open and compliant during that transition could prove to be one of the smartest decisions you make. The idea of working full time one day and stopping completely the next is losing its appeal.

Research by global advisory firm WTW found that nearly half of UK workers aged 50 and over have either started phasing into retirement or would like to, with most of those already doing so having reduced their hours.

Separate research from Aegon found that fewer than a third of over 50s now favour the traditional “cliff edge” approach.

The rising State Pension age is likely adding momentum to this movement as it rises from 66 to 67 between 2026 and 2028.

This means a longer wait for that income, however small it may seem and a greater need to bridge the gap.

Why consulting and contracting suits a gradual exit

Employees who want to wind down are often at the mercy of their employer’s appetite for part-time arrangements.

However, contractors are in a very different position, as you already set your own diary and negotiate your own rates.

A phased retirement might mean dropping from five days a week to two or three or moving to shorter assignments with much longer breaks between each one.

You may even change the roles you are looking at and move into more advisory work, where your knowledge can be put to better use.

It isn’t uncommon for some contractors or consultants to return to former clients on a reduced basis, providing continuity on projects they know inside out.

Whatever approach you choose to take, the main thing is you remain in control and can scale back or increase your workload to suit your finances.

The temptation to close the company

As work tails off, many contractors are tempted to tidy things up by closing their personal service company (PSC).

A members’ voluntary liquidation (MVL) can look like a neat way to extract retained profits and draw a line under things.

For someone who has genuinely finished working, that may be the right move, but for many others who simply intend to work less, closing too early can be costly in both financial and practical terms.

Here are some of the reasons why:

Always ready for the next opportunity – An established company with a trading history, business bank account, insurance cover and VAT registration already in place lets you accept work at short notice.

Agencies and end clients are generally comfortable engaging an existing company, whereas setting up again from scratch takes time you may not have when a good contract appears.

You avoid the two-year trap – Where an MVL qualifies for Business Asset Disposal Relief (BADR), capital gains on qualifying distributions are taxed at a reduced rate, subject to a lifetime limit of £1 million. That rate is now 18 per cent following the increase on 6 April 2026, having been 10 per cent before April 2025.

However, a targeted anti-avoidance rule allows HMRC to treat a distribution as income, taxed at dividend rates, if you carry on a similar trade or activity within two years of the winding up. That includes working as a sole trader or through a new company. For a contractor who is not yet certain they have stopped for good, this is a real risk and keeping the company open helps to avoid this issue.

You can draw profits more efficiently – Retained profits can be extracted over several tax years, timed to coincide with years when your other income is lower.

This matters more since dividend tax rates rose by two percentage points in April 2026, to 10.75 per cent for basic rate taxpayers and 35.75 per cent for higher rate taxpayers. Spreading withdrawals of retained profits, where possible, across a lower-earning period may keep more of that income within the basic rate band.

You keep an efficient route into your pension – Employer pension contributions made by your company are generally deductible for Corporation Tax, provided they meet the wholly and exclusively test and they are not treated as employment income for you.

The standard annual allowance is £60,000 for 2026/27 and unused allowance from the previous three tax years can often be carried forward.

Just be mindful that once you flexibly access a defined contribution pension, for example by taking taxable income through drawdown, the Money Purchase Annual Allowance applies.

Future contributions to money purchase schemes are then capped at £10,000 a year and carry forward is no longer available. For phased retirees, the order in which you draw on your pension and your company is worth planning carefully.

Staying compliant as a director

Keeping the company open means us here at Cogent continuing to meet your obligations as a director, even in quieter years. Your responsibilities do not shrink in line with your turnover and we will still need to deal with the following on your behalf:

  • Annual accounts filed with Companies House
  • A Confirmation Statement at least once every 12 months
  • A company tax return and any corporation tax due
  • Your personal Self-Assessment return
  • Payroll and VAT returns where these apply

Jackdaw gas field approval opens doors for energy contractors

Jackdaw gas field approval opens doors for energy contractors

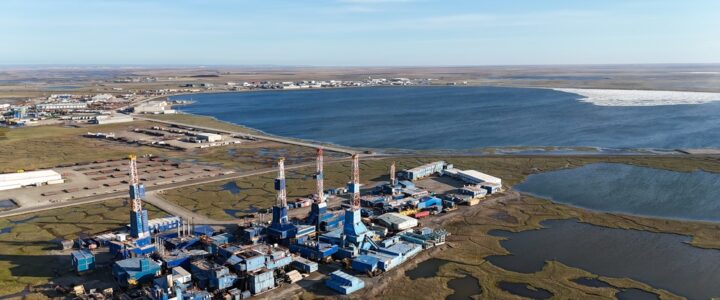
The Government has given the green light for gas production at the Jackdaw field in the central North Sea, east of Aberdeen.

For the many contractors and freelancers who work across the UK energy sector, it is a welcome signal that skilled offshore work is set to continue for years to come.

Announced on 21 October, Energy Secretary Miatta Fahnbulleh agreed that the North Sea Transition Authority (NSTA) can grant consent for production at the field, which is already licensed.

What has been approved

At its peak, Jackdaw is expected to increase domestic gas production by around six per cent. The field has a working life of up to 11 years and the developer, Adura, estimates it will add around £2.9 billion to the UK economy.

The decision follows the Supreme Court’s 2024 ruling in the Finch case, which requires operators to consider the emissions from burning the oil and gas they extract.

Having weighed this up, the Energy Secretary concluded that Jackdaw will not prevent the UK from meeting its legally binding carbon limits or its 2050 net zero target.

Good news for jobs

Adura estimates that Jackdaw will create 27 new direct jobs and safeguard 273 existing roles that would otherwise have been lost.

Behind those headline figures sits a wider supply chain of engineers, technicians, project managers and specialist consultants, many of whom work on a contract basis.

The field is also seen as important to extending the life of other North Sea infrastructure, including the Shearwater hub it connects to, which helps keep neighbouring assets and the work around them viable.

Wider opportunities for contractors

Jackdaw is one part of a bigger picture. Alongside the decision, the Government set out several measures that could create work for contractors well beyond a single gas field.

Decommissioning is one of the biggest and the Government expects the sector to support up to 25,000 skilled jobs over the next decade and attract up to £25.6 billion in investment.

It has launched a consultation on new guidance for decommissioning complex infrastructure and formally asked Shell to submit its Brent decommissioning programme, a decision that has been under review since 2017.

For existing fields, the Government is asking the regulator to look at urgent cases for developing already explored areas near licensed fields, ahead of legislation on new Transitional Energy Certificates. Talks have also begun with industry leaders on a refresh of the North Sea Transition Deal.

On the renewables side, the Chancellor has announced a new Energy Wealth Fund, starting with a £2 billion injection, which will reinvest North Sea tax revenues in renewable and low carbon projects.

More than £100 billion has been invested in renewable and low carbon energy since 2024 and this week alone SSE confirmed supply chain contracts for the Berwick Bank B offshore wind farm that will support 400 skilled jobs across Scotland.

Many of the skills used offshore transfer well into decommissioning and offshore wind. For contractors, that points to a broader and more stable pipeline of work as the sector changes.

What contractors should think about now

If you are lining up new work on the back of these announcements, a little planning now can make a real difference.

  • IR35 – Review the status of every new engagement. Where a medium or large client is issuing a status determination, make sure it reflects how you actually work.
  • Expenses – Keep clear records of travel and accommodation costs. What you can claim depends on how each engagement is set up, so it pays to check before you start.
  • The Budget – The Energy Wealth Fund was announced ahead of the Budget, which may bring further changes for contractors and small businesses. Keep an eye on the detail when it lands.

Whether you already work in the energy sector or are thinking about moving into it, the Cogent team can help you get your finances set up properly from the start.

Send us your Self-Assessment Tax Return Questionnaire by 30 September and benefit from the full discount

***PLEASE IGNORE THIS REMINDER IF YOU HAVE ALREADY SENT US YOUR QUESTIONNAIRE***

If you would like Cogent to prepare and file your 2025/26 tax return and you have not yet sent us your completed Self-Assessment Tax Return Questionnaire, you will need to do so by 30 September 2026 to benefit fully from our discounted fee.

If you have a second shareholder, they may also need to file a tax return, even if they haven’t previously. For further advice, please contact our Tax Department.

The standard charge including VAT for a basic tax return is £270. Questionnaires received by 30 September 2026 will receive the full discount on a basic tax return, charged at £99.

If your questionnaire is received between 1 October and 31 December 2026, the fee will be discounted to £150; any returns received after 31 December 2026 will be charged at the full rate of £270.

Please note, that more complicated tax returns where additional work or supplements are required, will be subject to additional charges.

Our deadlines have been set so that we can complete your return in time to meet the HM Revenue & Customs’ (HMRC) online filing deadline of 31 January 2027.

Penalties for late filing of tax returns can be as much as £1,600, even when there is no tax due, so please ensure your tax return is filed on time, whether you ask us to prepare it for you, or you have made other arrangements.

You can request a questionnaire for 2025/26 by emailing tax@cogentaccountants.co.uk

Please return your completed questionnaire together with any attachments by email only to our Tax Department – tax@cogentaccountants.co.uk

You are required to file a tax return if:

  • You have been asked to file one by HMRC
  • You have a tax liability for the year (e.g. additional and higher rate tax, student loan repayments, high-income child benefit charge or if you have any income which has not been taxed at source)
  • You have a new source of income that needs to be declared.

***PLEASE IGNORE THIS REMINDER IF YOU HAVE ALREADY SENT US YOUR QUESTIONNAIRE*** 

This is your final call – Companies House Identity Verification Process deadline reminder

The Companies House ‘Identity Verification Process’ launched last year on 18 November 2025, making it a legal requirement for new and existing Company Directors and Persons with Significant Control (PSCs) to verify their identity over a 12-month period, as and when their company’s annual Confirmation Statement and PSC ID are due for filing.

This verification process helps deter those wishing to use companies for illegal purposes.

Anyone setting up, running, owning or controlling a company in the UK needs to verify their identity over this 12-month period in order to prove they are who they claim to be.

We have been writing to clients over the past 10 months when it was time for us to file their company’s annual Confirmation Statement and PSC ID, with full details of how to apply to Companies House for their unique filing code.

All current clients should have received an email from us by now – reminders are going out weekly to those still outstanding, these should be attended to without delay.

If you haven’t done so already, it is extremely important that you forward the unique filing code to us as soon as it has been received from Companies House, as we are unable to file the company’s Confirmation Statement and PSC ID without it and this may incur unnecessary late filing fines and penalties.

Back to work: Making the most of the months ahead

The kids are back at school, the summer holidays already feel like a distant memory and life is slowly settling back into its usual rhythm.

September always feels like a bit of a reset, a chance to get back into the swing of things after (hopefully) a bit of sun, sea or at least a break away from the day-to-day.

For contractors and freelancers, it’s also a great moment in the year to pause, take stock and get set for a strong finish to 2026.

Check in on your contracts

Take a quick look at your current agreements. Are your rates still competitive? Do the terms still work for you now, compared with when you signed?

A little review now can save you headaches later and might even open the door to better deals going forward.

If nothing else, it will help you understand what you should be looking for in your next contract, as and when it comes around.

See what work is coming in

Autumn tends to be a busy time as projects kick off after the summer lull. Take a look at your pipeline and see whether there’s enough coming in to keep you busy through to the year end.

If not, now is the perfect time to start reconnecting with former clients and letting your network know when you’re next available for work.

Marketing yourself well ahead of the end of a contract should help you avoid any gaps in employment, if that’s what you want to achieve.

Shout about yourself

When was the last time you refreshed your LinkedIn (be honest)? As people settle back into work, they tend to spend a bit more time on their social media, often as a welcome distraction from getting back into their role.

Now is a great time to share some recent wins and remind people what you do best. You may even get ahead of the competition, as many freelancers wait for the usual “new year, new job” posts in January.

Plan for what’s next

Think about how you want the rest of the year to look. Set aside some time for financial planning, make sure you’re on top of your tax position and start thinking ahead to 2027.

With the Autumn Budget on the horizon, taking time now to consider its potential impact on your finances and how you operate is well worth it, even before we know the detail of the Chancellor’s speech.

Coming back after summer isn’t just about catching up, it’s about getting ahead. By checking in on your contracts, promoting yourself and doing some simple planning, you can put yourself in a great position to end the year on a high.

Complete your 2025-26 Tax Return Questionnaire

***PLEASE IGNORE THIS REMINDER IF YOU HAVE ALREADY SENT US YOUR QUESTIONNAIRE***

We sent out our 2025-26 tax questionnaires on 15 May and if you would like Cogent to prepare and file your 2025-26 tax return, please send us your completed Self-Assessment Tax Return Questionnaire.

If you have a second shareholder, they may also need to file a tax return, even if they haven’t previously. For further advice, please contact our Tax Department.

The standard charge including VAT for a basic tax return is £270. Questionnaires received by 30 September 2026 will receive the full discount on a basic tax return, charged at £99.

If your questionnaire is received between 1 October and 31 December 2026, the fee will be discounted to £150; any returns received after 31 December 2026 will be charged at the full rate of £270.

Please note, that more complicated tax returns where additional work or supplements are required, will be subject to additional charges.

Our deadlines have been set so that we can complete your return in time to meet the HM Revenue & Customs’ (HMRC) online filing deadline of 31 January 2027.

If you have any queries or haven’t received the questionnaire, please contact our tax department by emailing tax@cogentaccountants.co.uk

Please return your completed questionnaire together with any attachments by email to our Tax Department – tax@cogentaccountants.co.uk

***PLEASE IGNORE THIS REMINDER IF YOU HAVE ALREADY SENT US YOUR QUESTIONNAIRE***

Do you have retained profits? The benefits of high-interest rate accounts

If your company has retained profits and you have no immediate plans to use them, investing in a high-interest account or company bond is a great way to boost your funds.

High-interest rate accounts

Higher interest rate accounts enable you to earn more from your retained profits than would be possible from a regular business current or savings account.

However, in return for higher interest on your cash, you will typically need to leave your funds untouched in the account or bond for a set period.

As a rule, the longer the period, the more interest you’ll be able to earn. If you end up withdrawing the money early, you will likely face substantial penalties.

That’s why you need to consider how much of your retained profits you can safely invest in a fixed higher interest rate savings account.

Advice for contractors

As a contractor, you face periods of uncertainty. If you may need all your retained profits to keep your business afloat through tougher financial periods, tying up your funds in a fixed account could lead to further issues and higher costs down the line.

That’s why you must make sure that you set enough funds aside that are easily accessible to you before transferring any retained profits into a high-interest rate account.

If you’re planning your exit strategy, accumulating retained profits in a high-interest rate account can be an effective way of reducing your tax liability upon distribution of the company’s capital.

In any event, you should always seek independent financial advice before you make any significant investment decisions.

We have a wealth of experience in advising contractors just like you on the best use of their retained profits and can refer you to independent financial advisers who can help. If you’re struggling to work out what’s best for your business, speak to us.

School’s out: How to use the summer to reset your contracting business

As schools break up and inboxes start to go quiet, many contractors get something they rarely have during term time – a bit of breathing space.

Whether you’re jetting off or just enjoying a slower week, summer is a natural pause point – one that shouldn’t be squandered.

Rest doesn’t have to mean doing nothing, it can also mean taking stock of where your business stands and coming back sharper for it.

Review your contracts

When did you last actually read through your current contracts, rather than just checking the dates? It’s worth looking beyond deadlines to ask:

  • Are your rates still fair, given the value you’re delivering?
  • Do your terms actually protect you if a project goes wrong?
  • Are there clauses you keep signing without a second thought, that you’d now negotiate differently?

A proper read-through of your agreements with clients, suppliers or agencies often turns up gaps you’d otherwise only notice when it’s too late to fix them.

While you’re at it, check for auto-renewal dates and upcoming notice periods, so nothing rolls over without you meaning it to.

Warm up your pipeline

A quieter summer is a good moment to reconnect, not just recharge.

A few small actions can go a long way:

  • Give your portfolio or website a refresh
  • Drop a message to past clients, just to check in
  • Update recruiters on your availability
  • Have a look at industries or projects you’d like to move towards next

One well-timed message can be enough to land your next contract, or simply keep you front of mind when the right opportunity comes up.

Check in on your numbers

It’s easy to settle into a rhythm of earn, invoice, repeat once you’re busy, but that doesn’t tell you how healthy the business actually is underneath.

Use the quieter weeks to get a proper look at:

  • Whether you’re setting aside enough for tax and any gaps between contracts
  • Whether your pricing still stacks up against your costs and time
  • Which clients or projects are genuinely the most profitable, once everything is accounted for

Tidy up how you work

A summer reset isn’t just about contracts and cashflow, it’s also a chance to look at how your business runs day to day.

Small changes, like automating your invoicing or simplifying your expense tracking, can free up hours you didn’t know you were losing and make the next busy stretch easier to manage.

Don’t forget to actually switch off

Not everything about summer needs to be productive. Your business’s biggest asset is you and that means it’s worth properly looking after.

Read something that isn’t work-related or go somewhere new, as some of the best ideas turn up when you’ve stopped chasing them.

You don’t need to overhaul your business this summer. A few thoughtful tweaks, made while things are quiet, can carry you a long way into the next busy season.

Review what’s working, fix what isn’t and give yourself permission to properly rest.

CAPTCHA image